October 29, 2026 · Emre Kurt, Lawyer
Greece 15% Transfer Tax: Who Pays, Who Is Exempt (July 2027)
15% transfer tax for non-EU buyers in Greece: who pays, who may be exempt, is a reservation enough, Golden Visa extra cost and the pre-July 2027 timeline.
The Greek government plans to raise the property transfer tax on home purchases by natural persons who are nationals of non-EU and non-EEA countries from 3% to 15% (including the municipal surcharge, from 3.09% to approximately 15.45%). The announced effective date is 1 July 2027. This directly affects buyers from Turkey, the UK, the US, China, India, the Gulf states, Russia and other non-EU countries, whatever their nationality, as well as Golden Visa investors. In this article, drawing on the Greek press and law firm sources, we explain who will pay the tax, who may be exempt, what “completion” means and what kind of timeline can be followed up to July 2027. We covered the first news in September in our tax signal article; this article covers the current status.
Important: This is an announcement, not a law. According to sources dated 14 and 21 October 2026, the bill has not yet been published and has not passed Parliament. Details may change. For information only; this is not legal or tax advice.
Short Answer
- Rate: For non-EU/EEA natural-person buyers, the transfer tax on residential property is 15% instead of 3% (~15.45% in total including the municipal surcharge).
- Date: Initially 1 January 2027 was stated; following the reaction, it was postponed to 1 July 2027. Purchases completed before that date will be subject to the current rate.
- Exempt (as announced): EU/EEA nationals, people of Greek descent (omogeneis, ομογενείς), and holders of long-term residence status (LTR) in Greece. Companies, commercial property and land are outside the scope.
- Golden Visa: The investment thresholds (€250,000, €400,000, €800,000) are not changing; however, the cost of reaching the threshold is rising. Whether the €250,000 conversion route will be granted an exemption or an intermediate rate (~8%) remains open.
- Status: The bill has not been published; it is expected to be put to public consultation in November. The transitional provisions are not known.
Timeline from the Announcement to Today
| Date | Development |
|---|---|
| Early September 2026 | The government announced that the transfer tax for non-EU/EEA buyers would be raised from 3% to 15% (6–7 September, according to a law firm source). In the first reports, the start date was 1 January 2027. |
| September–October 2026 | Following the reaction, the scope was narrowed: the start was postponed to 1 July 2027; people of Greek descent and LTR holders exempt; companies and non-residential property outside the scope. |
| 4 October 2026 | To Vima reported that the measure covers only natural persons, that the exemption criteria have not been clarified and that the bill has not been published. |
| 14 October 2026 | According to a law firm analysis, “the bill has not been published, nothing has passed Parliament”. The spring 2027 elections add uncertainty. |
| 21 October 2026 | According to a real estate report, the bill has still not been published or put to public consultation. |
| November 2026 (expected) | The multi-article bill containing the Thessaloniki International Fair (ΔΕΘ) package is expected to be put to public consultation. |
Sources: To Vima (4 October), Protothema, CretaOne, Katsouris Law Firm (14 October), Avla Real Estate (21 October 2026). The November expectation is a press report, not an official timetable.
Who Pays, and Who May Be Exempt?
| Buyer group | Status (as announced) | Note |
|---|---|---|
| Natural persons who are EU and EEA nationals | Exempt; 3% continues | The target group is non-EU buyers |
| Natural persons who are nationals of Turkey, the UK, the US, China, India, the Gulf states, Russia, etc. | Pay 15% | On residential purchases; if they do not hold LTR status |
| People of Greek descent (omogeneis, ομογενείς) | May be exempt | Descent must be documented; the definition is not yet clear |
| Holders of long-term residence status (LTR) in Greece | May be exempt | The definition of LTR and the required period are not yet clear |
| Companies and legal entities | Outside the scope | Anti-abuse rules may be introduced; the consequences of buying through a company should be assessed separately from a Golden Visa perspective |
| Commercial property, land and non-residential real estate | Outside the scope | The status of buildings converted to residential use has not been clarified |
A Golden Visa holder may move to long-term residence status at the end of 5 years; whether this status will be sufficient for the exemption is not known until the definition of LTR is clarified. For the LTR transition, see our LTR guide.
Extra Cost for the Golden Visa Investor
| Purchase price | Tax at 3.09% | Tax at 15.45% | Extra burden |
|---|---|---|---|
| €250,000 | €7,725 | €38,625 | €30,900 |
| €300,000 | €9,270 | €46,350 | €37,080 |
| €400,000 | €12,360 | €61,800 | €49,440 |
| €800,000 | €24,720 | €123,600 | €98,880 |
The tax base is the higher of the contract price and the property's official (objective) value; if the official value is higher than the contract price, the tax may be higher. Figures are approximate.
Even though the thresholds stay the same, this burden particularly affects purchases in the €250,000–400,000 range: the Greek sector is asking for an exemption or an intermediate rate of around 8% for the €250,000 conversion route, on the grounds that these investments create new housing stock. Whether this request will be accepted is not known. For all cost items, see our total cost guide.
What Does “Completion” Mean? Is a Reservation Enough?
According to the law firm analysis, ownership is transferred by signing the final deed of sale (notarial contract) before a notary and then registering it with the Land Registry/Cadastre. A reservation, deposit or preliminary contract (prosymfono, προσύμφωνο) does not transfer ownership. The property transfer tax is paid before the deed is signed. Unless the law states otherwise, the decisive date will be the date of the final deed, not the reservation date.
- No transitional provision: Because the bill has not been published, it is not known whether preliminary contracts signed before 1 July 2027 will be protected; sources recommend assuming they will not be.
- Construction/conversion projects: If the final deed is to be signed on delivery and delivery goes beyond June 2027, the extra tax may fall on the buyer. The contract should state in writing who bears this risk.
- Time margin: For a clean resale property, the legal check and paperwork usually take 2–4 months, and longer for unfinished buildings.
Timeline Before July 2027: Working Backwards
The table below gives a sample timeline worked backwards from the goal of signing the final deed by the end of June 2027. All durations are average estimates; they are not a legal guarantee.
| Goal | Approximate start | Rationale |
|---|---|---|
| Ready resale/ready-to-move-in apartment, deed in March 2027 | November–December 2026 | Legal check and paperwork 2–4 months |
| Ready apartment, deed in June 2027 (last minute) | February–March 2027 | No margin for delay; risky |
| Project under construction, delivery mid-2027 and later | Immediately; clarify the deed date in the contract | Delivery date ≠ deed date; who bears the extra tax risk? |
| Project with 2028 delivery | Assess the deed date and tax risk with a lawyer | If signing is required on delivery, you may face 15% |
Delivery dates differ across the projects on the site: some are ready, others are due January–March 2027 (Kerameikos, Larissa), mid-2027 (Kallithea Modern, Piraeus Modern) and 2028 (Elliniko, Moschato 2nd–3rd Floor, Marousi). These dates are delivery dates, not title deed dates; ask in writing when the deed will be signed for each project. For the list, see the projects page.
Scenarios: What Could Happen, and What Can Be Done?
| Scenario | Impact | What can be done? |
|---|---|---|
| The bill takes effect on 1 July 2027 | 15.45% for non-EU buyers | Bring the deed forward to before July; do not rely on the preliminary contract |
| An exemption or an intermediate rate of ~8% is introduced for the Golden Visa conversion route | The extra burden is reduced | Until a decision is made, ask for a tax-change clause in the contract |
| The date is postponed or the scope is narrowed | The timeline eases | Keep speeding up the planned legal check |
| The spring 2027 elections affect the bill | Uncertainty increases | Do not decide based on a single scenario |
6-Point Checklist for Buyers
- On what date will the deed be signed? Write the date of the final deed, not the reservation, into the contract.
- Tax clause in the contract: Specify who bears the extra tax in the event of a legal change, especially in projects delivered after construction.
- Ask about your exemption status: Do you have EU/EEA citizenship, Greek descent or LTR status? Can it be documented?
- Calculate the tax base: The tax is calculated on the higher of the contract price and the official (objective) value.
- Leave a margin in your timeline: The legal check can take 2–4 months; do not leave it to the last month.
- Do not rely on a single source: Once the bill is published, have your lawyer confirm the current text in writing.
For the legal check, see our due diligence guide; for the process timeline, our reservation-to-card guide; for common mistakes, our mistakes article. For the future of the programme, see our “Is It Ending?” article.
Let's take the right step toward your Greece Golden Visa together.
From choosing the right project to the application and residency, we are with you end to end.
Get a Free ConsultationFrequently Asked Questions
1. Has Greece's 15% transfer tax become law, and when does it start?
No, it has not yet become law. In September 2026 the government announced that the property transfer tax for non-EU and non-EEA natural-person buyers would be raised from 3% to 15% (approximately 15.45% including the municipal surcharge). The start date was initially announced as 1 January 2027; following the reaction, it was postponed to 1 July 2027. As of mid-to-late October 2026, the bill has not been published and has not passed Parliament. The bill is expected to be put to public consultation soon as part of a multi-article package; details and transitional provisions may change. Confirm the current text with your lawyer once it is published.
2. Who pays 15%, and who may be exempt?
As announced, the 15% will apply to home purchases by natural persons who are nationals of non-EU and non-EEA countries; this means nationals of Turkey, the UK, the US, China, India, the Gulf states, Russia and other non-EU countries are within scope. EU/EEA nationals, people of Greek descent (omogeneis, ομογενείς) and holders of long-term residence status in Greece may be exempt; the definitions of these groups and the required documents are not yet clear. Companies, commercial property and land are described as outside the scope, but anti-abuse rules may be introduced.
3. If I make a reservation or sign a preliminary contract, can I complete at the old tax rate?
This is not yet known. According to a law firm analysis, ownership is transferred by signing the final deed before a notary and registering it with the Land Registry/Cadastre; a reservation, deposit or preliminary contract does not transfer ownership, and the tax is paid before the deed. Because the bill has not been published, there is no transitional provision on whether preliminary contracts signed before 1 July 2027 will be protected; sources recommend assuming they will not be. Therefore, assume that the decisive date will be the date of the final deed, and make signing the deed before June 2027 a contractual commitment.
4. Are the Golden Visa investment thresholds changing, and is the €250,000 route affected?
Under the announcement, the Golden Visa investment thresholds (€250,000, €400,000, €800,000) are not changing; only the transfer tax is increasing, which means the cost of reaching the threshold is rising. The extra burden is approximately €30,900 at €250,000, approximately €49,400 at €400,000 and approximately €98,900 at €800,000. The Greek sector is asking for an exemption or an intermediate rate of around 8% for the €250,000 route, arguing that commercial buildings converted to residential use and restorations of listed buildings create new housing stock. Whether this request will be accepted is not yet known.
5. When should I start in order to buy before July 2027?
For a ready apartment, the legal check and paperwork usually take 2–4 months; if the deed is to be signed in March 2027, starting in November–December 2026 gives a reasonable timeline. Targeting June 2027 at the last minute leaves no margin for delay and is risky. For projects under construction, the problem arises if the final deed is signed on delivery: if delivery goes beyond June 2027, the extra tax may fall on the buyer. For this reason, ask in writing for the deed date for each project and clarify in the contract who bears the risk of a tax change.
Sources: To Vima (4 October 2026), Protothema, CretaOne, Katsouris Law Firm (14 October 2026), Avla Real Estate (21 October 2026), Law 5100/2024. For information only; this is not legal or tax advice. It should be updated once the bill is published.
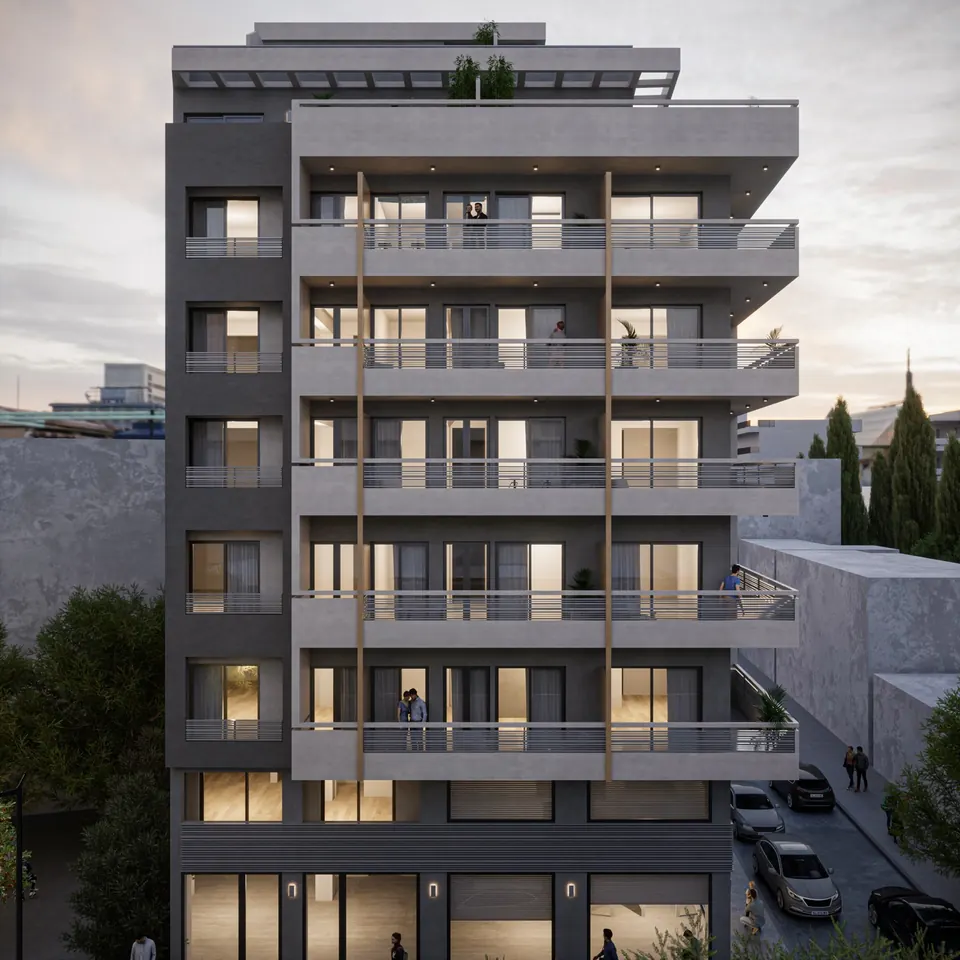 DELIVERY MAR 2027
Larissa Station · AthensGA-02
Larissa Station Residences
A €250,000 Golden Visa conversion beside Larissa Station in central Athens: 21 furnished residences with a gym and shared lounge.
- Beds
- Studio – 3 bed
- Energy Class
- —
- Delivery
- 2027
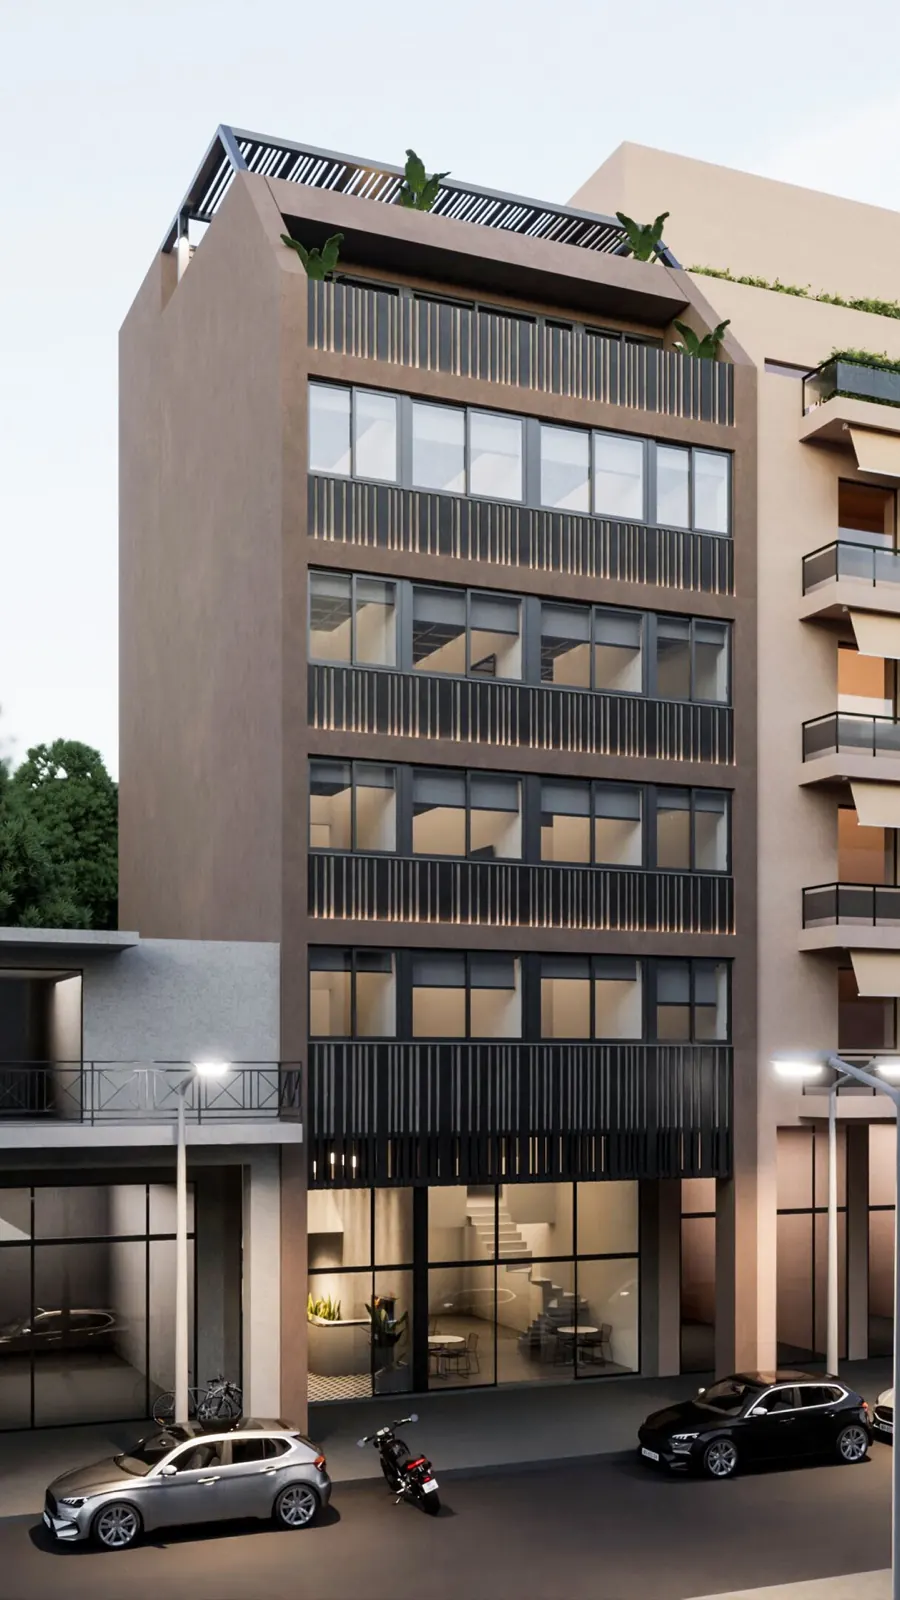 READY TO MOVE IN
Piraeus · AthensGA-04
Piraeus Furnished Apartments
A €250,000 Golden Visa conversion in the port city of Piraeus: ready, fully furnished apartments in a building with smart locks, a reception and a gym. Apartments bought for the Golden Visa can only be let long-term.
- Beds
- 1–2 bed
- Energy Class
- —
- Delivery
- Ready
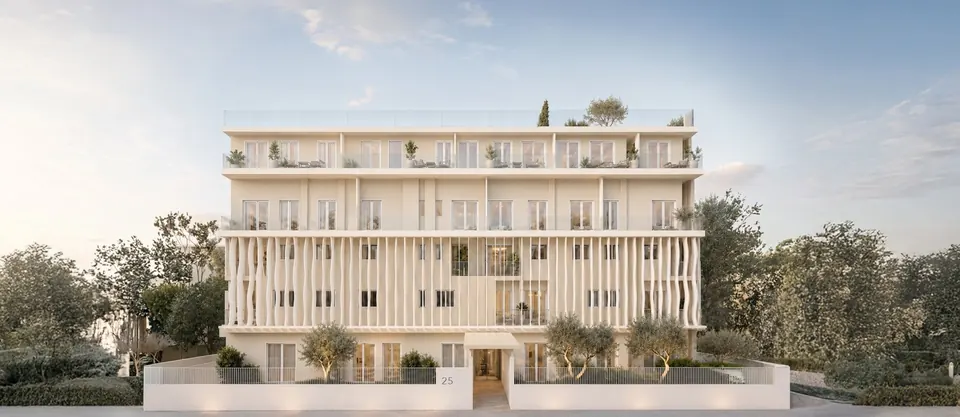
Agios Ioannis Rentis · PiraeusGA-40
Piraeus Garden Residences
A 72-apartment residential complex in Piraeus created by converting a commercial building: a courtyard with a reflecting pool, private garden, outdoor gym and a rooftop terrace with Acropolis and coastline views. 42–81 m², delivered furnished, eligible for the €250,000 Golden Visa.
- Beds
- 1–3 bed
- Energy Class
- —
- Delivery
- 2027