September 15, 2026 · Updated: October 7, 2026 · Emre Kurt, Lawyer
A New Tax Signal for the Golden Visa: Is the Transfer Tax Rising from 3% to 15%? (2026)
PM Mitsotakis's 6 Sept 2026 announcement: property transfer tax for non-EU buyers from 3.09% to 15% (≈15.45% effective), planned from 1 July 2027 — not yet law. Scope and the Golden Visa impact.
Speaking at the Thessaloniki International Fair on 6 September 2026, Prime Minister Kyriakos Mitsotakis announced that the transfer tax applied to property purchases by non-EU nationals will rise from 3% (effectively 3.09%) to 15% (about 15.45% effective with the municipal surcharge); the new rate is planned to apply from 1 July 2027, but the measure is not yet law. This is a development that will directly affect almost every Golden Visa investor — because, by definition, the programme is open only to third-country nationals. In this article we explain the full scope of the announcement, the planned start date, and how this change could affect your Golden Visa strategy, with the latest information.
Key Elements of the Announcement
| Element | Detail |
|---|---|
| Current Rate | 3.09% (on the higher of the sale price or the objective value) |
| New Rate (announced) | 15% (≈15.45% effective with the 3% municipal surcharge on the tax) |
| Who Is Covered | Non-EU/EEA nationals (third-country nationals) — all Golden Visa investors fall within this scope |
| Announced Start Date | Planned from 1 July 2027 (not yet law) |
| Legal Status | Not yet law — must pass Parliament and be published in the Government Gazette |
Critical Warning: This Is Not Yet Law
As noted in the table above, the bill text and the exact start date have not yet been officially published. The Prime Minister's statement was made as part of a broad €2.2 billion economic and housing package; the package also includes a €2 billion subsidised mortgage programme, phased reductions in electricity costs and the abolition of the ENFIA property tax in small settlements. But this is at the stage of a political announcement; the law must pass Parliament and be published in the Government Gazette. The fact that Greece's next general election is expected by 2027 at the latest adds further uncertainty as to whether the law will pass in this final form.
There is an announced plan for the start date, but no binding date yet: Finance Minister and Eurogroup President Kyriakos Pierrakakis stated that the new rate is planned to apply from 1 July 2027. As no bill text has been published, this date is for now only a plan; the exact date will only become clear when the bill text is published.
Which Properties Are In Scope, and Which Are Out?
The most critical technical detail of the announcement is that the scope is limited to residential property only (as no bill text has been published, the split below is based on the announcement and is not yet final). This distinction has important strategic consequences for Golden Visa investors:
| Property Type | Affected? |
|---|---|
| Standard Residential (€400K/€800K route) | YES — will be subject to 15% |
| Conversion Home (€250K Zone C route) | YES — subject to 15% because the outcome is residential (hits the cheapest route too) |
| Commercial Property / Office / Warehouse | NO — stays at 3.09% |
| Land | NO — stays at 3.09% |
| Hotel | NO — stays at 3.09% |
| Fund / Bond / Deposit Routes | NO — this tax covers real-estate transactions only; financial routes are entirely outside it |
What stands out here is that the €250,000 Zone C conversion route is also subject to the new rate. Some commentators initially thought this route might be classified as a "commercial property purchase" and exempted; but since the final outcome of a conversion is a home, this route too falls under the 15% rate. This means the programme's lowest-budget and most accessible route will carry the same tax burden — a development that could fundamentally change the cost balance of the option our conversion-route articles presented as the "most attractive opportunity".
The Concrete Cost Impact
Let's make it concrete with an example: on an €800,000 Athens Golden Visa purchase, the tax paid at the current 3.09% rate is roughly €24,720, while at the new 15% rate — about 15.45% effective with the municipal surcharge — it rises to roughly €123,600: an additional cost of roughly €98,900 on a single transaction. On a €400,000 Zone B purchase the difference is roughly €49,400 (€61,800 – €12,360); on a €250,000 Zone C conversion, roughly €30,900 (€38,625 – €7,725) of extra burden. (As the measure is not yet law, these figures are based on the announced rate.) These figures push the standard 8-10% additional-cost ratio covered in our total-cost articles significantly upward.
Why Is This Change Being Made?
In his speech, the Prime Minister explicitly described the measure as a "disincentive". He stated that heavy demand from countries such as Turkey, China and Israel makes it harder for Greek citizens to become homeowners in their own areas. This continues the theme covered in our 2024-reform and €800,000 regions article: the government does not want to stop foreign investment entirely, but to rebalance it in a way that reduces pressure on the local housing market.
Does It Affect Golden Visa Eligibility?
An important clarification: this tax change does not alter the Golden Visa's investment thresholds (€250K/€400K/€800K). A property's Golden Visa eligibility will continue to be determined by the investment amount and the zone classification; the transfer tax is a separate cost item added on top of that threshold. So if a property still meets the €800,000 threshold, it remains eligible for the Golden Visa — only the total cost of buying that property will have risen significantly once the new tax takes effect.
Are Non-Property Golden Visa Routes Affected?
No — this measure covers real-estate transactions only. The financial routes detailed in our fund/bond alternative article — the €350,000 investment fund, the €500,000 bank deposit or government bonds — fall entirely outside this tax increase. In current market conditions, this is a development that could increase the relative appeal of the financial routes.
What to Do Now?
- Since the law is not yet in force, the current 3.09% rate remains valid for now.
- Investors who complete their transaction before the planned start date (1 July 2027) will probably continue to benefit from the current lower rate — but how transitional provisions will be arranged is not yet known.
- Investors already in a Golden Visa process, or planning to start soon, are advised to review their transaction timeline with this development in mind.
- Because the law is not final, the healthiest approach right now is to follow developments closely and review the situation regularly with a lawyer, rather than making a panic purchase or a postponement decision.
- A lawyer, Alexander Risvas, has publicly stated that he questions the legal validity of this measure; this strengthens the possibility that the final form of the law may differ from the current announcement.
Let's take the right step toward your Greece Golden Visa together.
From choosing the right project to the application and residency, we are with you end to end.
Get a Free ConsultationFrequently Asked Questions
1. Is the transfer tax really rising to 15% — is it final?
Not yet. Prime Minister Kyriakos Mitsotakis announced the increase at the Thessaloniki International Fair on 6 September 2026, but the bill text and the exact start date have not been officially published. The measure must pass Parliament, and how that process unfolds before the general election expected by 2027 at the latest remains uncertain. The current 3.09% rate stays in force until the law officially changes.
2. When is the new rate due to start?
Under the announced plan, the new rate is due to apply from 1 July 2027; Finance Minister Kyriakos Pierrakakis also cited this date. But this is only an announced plan: no bill text has been published and the measure is not yet law. The exact date will only become clear when the official bill text is published, so following developments closely is important.
3. Is the €250,000 conversion route also subject to this tax?
Yes — perhaps the most critical and least expected detail. Because the €250,000 Zone C conversion route (commercial-to-residential) ultimately produces a residential property, under the announced scope it will be subject to the new 15% rate (≈15.45% effective); only genuine commercial properties (offices, warehouses, land, hotels — those whose use does not change) stay at 3.09%. This means the programme's most accessible, lowest-budget route will carry the same tax burden; contrary to some early commentary, this detail does not automatically exempt the conversion route.
4. Does this change affect the Golden Visa investment thresholds (€250K/€400K/€800K)?
No. This tax change does not alter the Golden Visa's own investment thresholds; those fall under a separate legal framework (Law 5100/2024). The transfer tax is an independent cost item added on top of the threshold. A property that still meets the relevant threshold (for example €800,000) remains eligible for the Golden Visa; but the total cost of buying that property will have risen significantly once the new tax takes effect.
5. If I apply via the fund or bond route, am I affected?
No — this measure covers real-estate transactions only. Financial Golden Visa routes such as the €350,000 investment fund, the €500,000 bank deposit, government bonds or corporate bonds/shares fall entirely outside this tax increase, because they involve no property transfer. Against the prospect of rising property costs, this can be seen as a factor increasing the relative appeal of the financial routes.
Note: The information in this article is based on a political announcement that has not yet become law and may change significantly; it does not constitute legal or financial advice. Contact us to assess together how this development may affect your investment timeline and to follow developments closely — we are with you from the start to the end of the Golden Visa process.
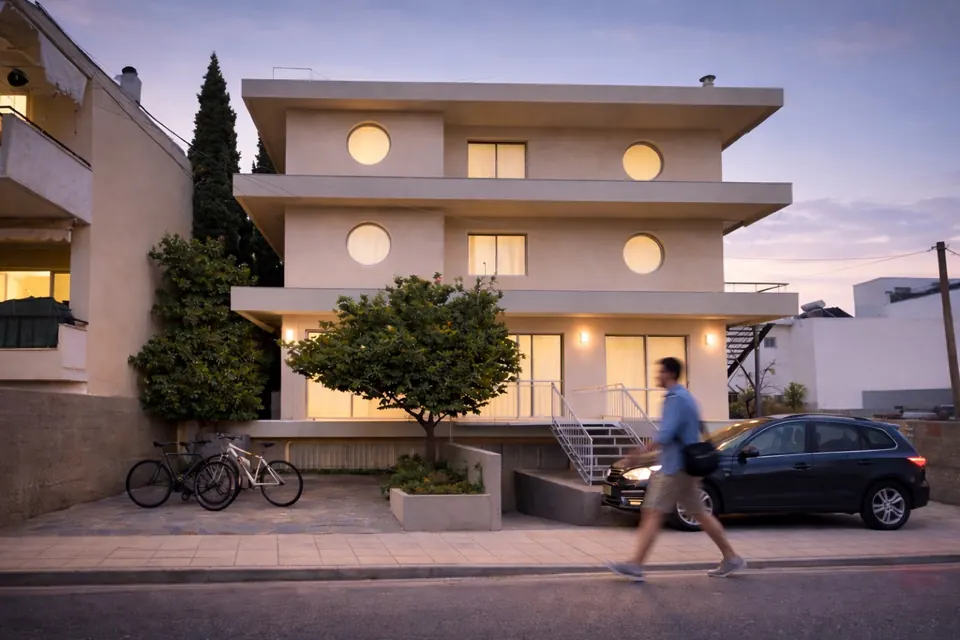
Gerakas · AthensGA-19
Gerakas Residences
A €250,000 Golden Visa conversion in Gerakas — an office turned into homes: compact one-bedrooms from €250,000.
- Beds
- 1 bed
- Energy Class
- —
- Delivery
- 2027
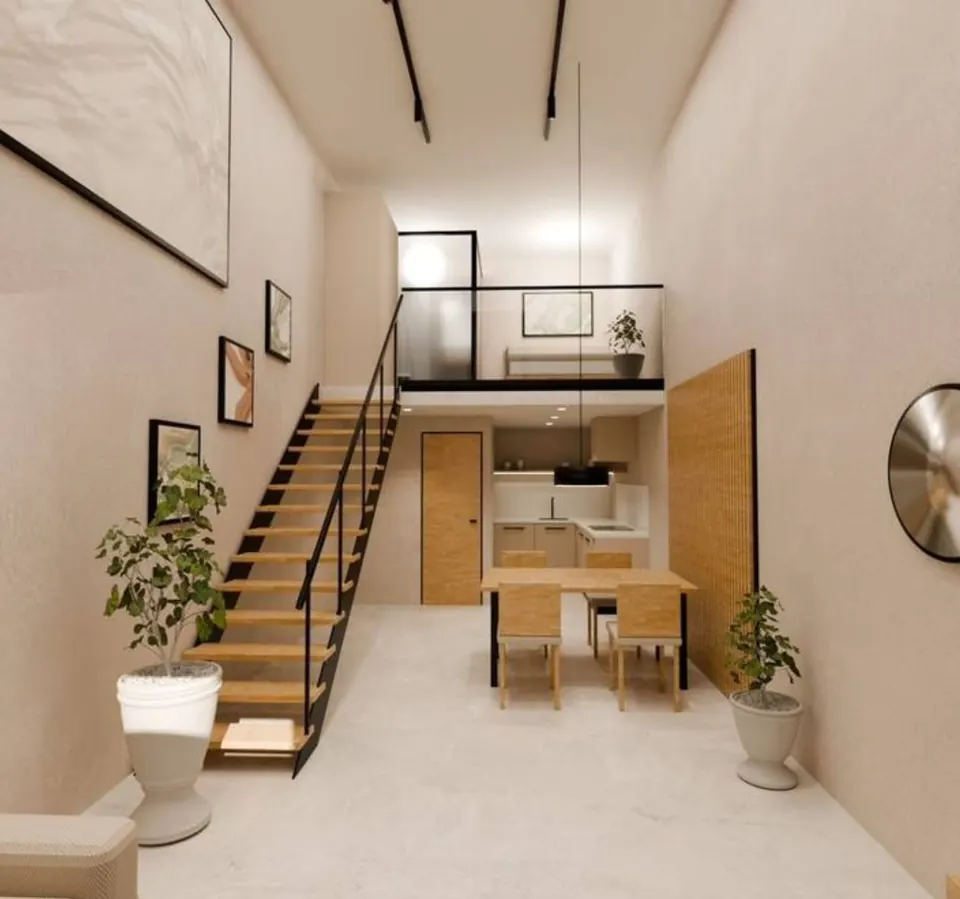
Thessaloniki Centre · ThessalonikiGA-51
Thessaloniki City Centre Twin Lofts
Two lofts in central Thessaloniki being converted from commercial to residential use: about 70 m² each, with a double-height living space and a mezzanine bedroom. Each is Golden Visa eligible at €250,000.
- Beds
- 1 bed
- Energy Class
- A
- Delivery
- Under renovation · date on request
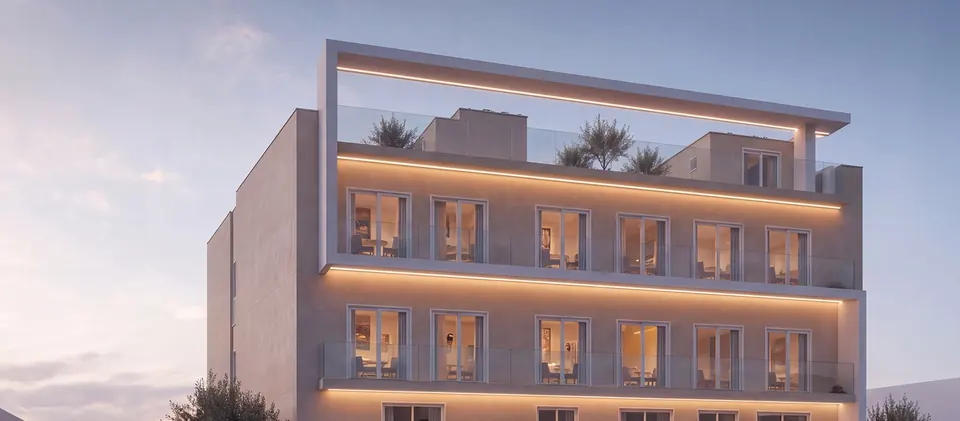
Peristeri · AthensGA-41
Peristeri Residences
A boutique project in Peristeri, a lively district of west Athens, where an older building is being converted into 14 apartments: 32–65 m², mostly two-bedroom, delivered furnished, with a top-floor apartment featuring a private roof terrace. Eligible for the €250,000 Golden Visa, €250,000–292,500.
- Beds
- 1–2 bed
- Energy Class
- —
- Delivery
- 2027