September 4, 2026 · Updated: October 7, 2026 · Emre Kurt, Lawyer
Greece Golden Visa Tax Residency Requirements
The Golden Visa does not create tax residency. The 183-day rule, the centre-of-life test and the Non-Dom/pensioner/new-resident special tax regimes in this 2026 guide.
Being a Golden Visa holder does not automatically mean being a Greek tax resident; this is one of the program's most frequently misunderstood but most important advantages. Tax residency, independent of the residence permit, depends entirely on physical presence time and the "centre of life" test. In this article we explain, with current 2026 information, how the 183-day rule works, its retroactive effect, and the special tax regimes Greece offers to high-net-worth investors.
The Basic Rule: The Golden Visa Is Not Tax Residency
Having the Greece Golden Visa does not automatically make a person a Greek tax resident. Tax residency is a completely separate assessment and rests on two fundamental criteria: the number of physical days spent in Greece within any 12-month period, and where the person's "centre of life" (permanent home, family) is. This distinction gives Golden Visa investors important flexibility; residence permit rights and tax obligations can be managed independently of each other.
The 183-Day Rule
A person who stays more than 183 days in Greece within any 12-month period is considered a Greek tax resident. This count starts not from 1 January but from the date the person actually enters Greece. When the threshold is exceeded, an important technical detail comes into play: residency applies retroactively back to the first day of the relevant period; that is, the assessment is not "I am a resident from the moment I passed the 183rd day" but "as if I had been a resident from the start of that year."
Under and Over 183 Days: A Comparison
| Situation | Under 183 Days | Over 183 Days |
|---|---|---|
| Tax Residency | Not a Greek tax resident | Greek tax resident |
| Taxable Income | Only Greek-source income | All worldwide income |
| Tax Rate | Standard rate applied only to Greek-source income | 9-44% progressive (or a special regime) |
| Retroactive Effect | None | When exceeded, applies back to the first day of the period |
The "Centre of Life" Test: An Alternative Trigger
Besides the number of physical days, if a person's permanent home or family is in Greece, that person can be considered a tax resident under the "centre of vital interests" test even if they stay under 183 days. Tracking only the day count may therefore not be enough; family settlement, permanent housing and the concentration of economic ties in Greece are also considered in the residency assessment.
Greece's Special Tax Regimes
Greece offers three separate special tax regimes for high-net-worth investors, pensioners and new residents. These regimes are optional, each addressing a different profile and strategy:
| Regime | Advantage | Main Requirement |
|---|---|---|
| Non-Dom (Article 5A) | Flat €100,000/year tax on foreign income, up to 15 years | €500,000 investment (within 3 years) + not a resident in 7 of the last 8 years |
| Pensioner (Article 5B) | Flat 7% tax on foreign pension income | Pensioner status, relocation to the country |
| New Resident (Article 5C) | 50% of Greek income exempt for 7 years | 183+ days/year actual residence MANDATORY |
The Non-Dom Regime (Article 5A): For High-Net-Worth Investors
This regime allows paying a flat €100,000 tax per year instead of standard progressive tax on all foreign income; this can offer an important advantage for investors with very high foreign income. The regime is valid for up to 15 years and requires an additional €20,000 per year for each additional family member. To benefit from this regime, an investment of at least €500,000 within three years and not having been a Greek tax resident in 7 of the last 8 years are required.
The Pensioner Regime (Article 5B)
Foreign pensioners who settle in Greece and become Greek tax residents can pay a flat 7% tax on foreign-source pension income instead of the standard progressive rate. This offers an important advantage compared with the standard 9-44% progressive rate and is especially attractive for pensioner investors.
The New Resident/Entrepreneur Regime (Article 5C)
This regime exempts 50% of Greek-source employment or self-employment income from tax for 7 years. But there is an important point to note here: unlike the other two regimes, benefiting from this one requires actual presence in Greece for at least 183 days a year. This offers an incentive structure that is the opposite of the "stay little, pay no tax" logic; a regime designed for people who genuinely plan to settle and work in Greece.
Other Important Points
- Greece has no general wealth tax; taxation applies to specific assets (like real estate), not total net worth.
- Greece has a broad treaty network to prevent double taxation; this provides important protection for investors earning income abroad.
- There is no mandatory tax regime for the Golden Visa itself; one can operate within the standard rules (the 183-day threshold) without applying to any of the special regimes above.
- If citizenship is the goal, a requirement of at least 183 days of actual residence per year over 7 years comes into play; but there is no such physical presence requirement just to keep the residence permit.
- A Golden Visa holder earning rental income in Greece is liable to pay tax in Greece on this income regardless of their tax residency status.
Let's take the right step toward your Greece Golden Visa together.
From choosing the right project to the application and residency, we are with you end to end.
Get a Free ConsultationFrequently Asked Questions
1. If I get the Golden Visa, do I automatically become a Greek tax resident?
No, having the Golden Visa does not automatically make you a Greek tax resident. Tax residency is a completely separate assessment from the residence permit and depends mainly on the number of physical days you spend in Greece within any 12-month period (the 183-day threshold) or where your "centre of life" (permanent home, family) is. A Golden Visa holder who stays under 183 days and whose centre of life is in another country is taxed in Greece only on Greek-source income (e.g. rental income), not on worldwide income.
2. What happens if I exceed the 183-day threshold?
If you stay more than 183 days in Greece within any 12-month period, you are considered a Greek tax resident and your worldwide income becomes subject to Greece's progressive rates of 9-44%. An important technical detail: this residency applies retroactively not from the moment you exceed the 183rd day but back to the first day of the relevant period (usually starting from your entry date). Carefully tracking the number of days you spend in Greece is therefore important to avoid unintentionally becoming a tax resident.
3. Who is the Non-Dom regime suitable for?
The Non-Dom regime (Article 5A) is designed for investors with high foreign income; by paying a flat €100,000 tax per year, it exempts all worldwide income from standard progressive tax. This regime is valid for up to 15 years and requires an additional €20,000 per year for each additional family member. To qualify, an investment of at least €500,000 within three years and not having been a Greek tax resident in 7 of the last 8 years are required. This regime can be advantageous especially for investors with high foreign income who plan to actually spend time in Greece.
4. Do I need to stay 183 days in Greece to keep the Golden Visa?
No, there is no physical presence or day-count requirement just to keep the residence permit; this is one of the program's important advantages. The 183-day threshold only applies to determining your tax residency status; it does not affect the validity of the residence permit. However, if your ultimate goal is to obtain Greek citizenship, then a requirement of at least 183 days of actual residence per year over 7 years comes into play. It is therefore important to distinguish the physical presence requirements between "simple residency" and "the road to citizenship".
5. If I earn rental income in Greece, do I pay tax regardless of my tax residency?
Yes, rental income earned in Greece is taxable in Greece regardless of your tax residency status. Even a person who stays under 183 days and is not considered a Greek tax resident is liable to pay tax in Greece on Greek-source income (like rental income); only their other worldwide income stays outside this taxation. So if you rent your Golden Visa property long-term, remember that you must file a tax return in Greece for this rental income regardless of your tax residency status.
Note: The tax information in this article is based on general regulations and can vary significantly by your personal situation; it does not constitute tax advice. Contact us to determine your tax residency strategy and the special regime suitable for you.
Thessaloniki Centre · ThessalonikiGA-51
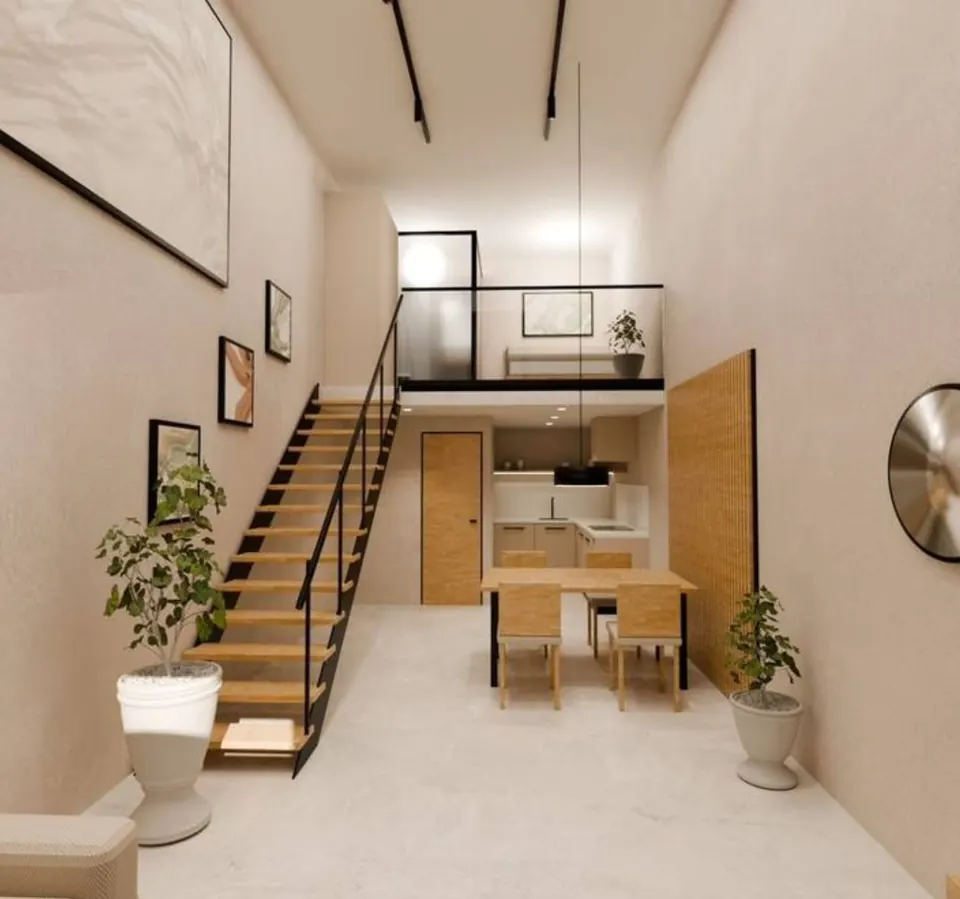
Thessaloniki City Centre Twin Lofts
Two lofts in central Thessaloniki being converted from commercial to residential use: about 70 m² each, with a double-height living space and a mezzanine bedroom. Each is Golden Visa eligible at €250,000.
- Beds
- 1 bed
- Energy Class
- A
- Delivery
- Under renovation · date on request
Peristeri · AthensGA-41
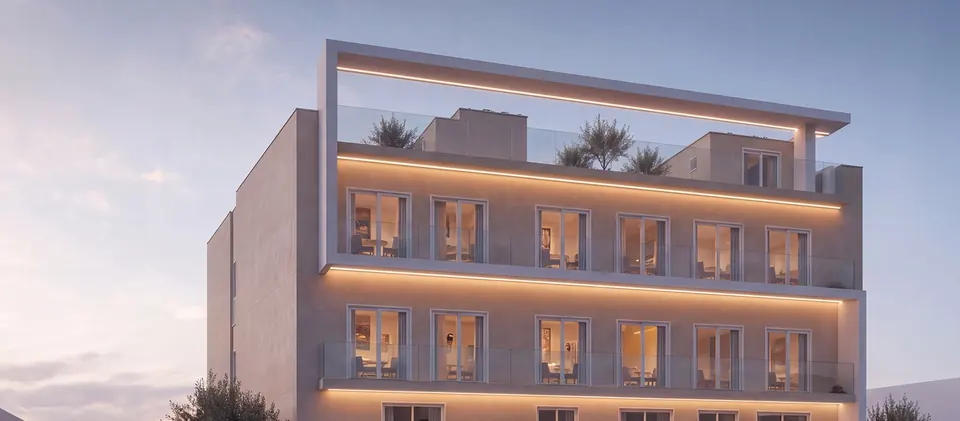
Peristeri Residences
A boutique project in Peristeri, a lively district of west Athens, where an older building is being converted into 14 apartments: 32–65 m², mostly two-bedroom, delivered furnished, with a top-floor apartment featuring a private roof terrace. Eligible for the €250,000 Golden Visa, €250,000–292,500.
- Beds
- 1–2 bed
- Energy Class
- —
- Delivery
- 2027
Gerakas · AthensGA-19
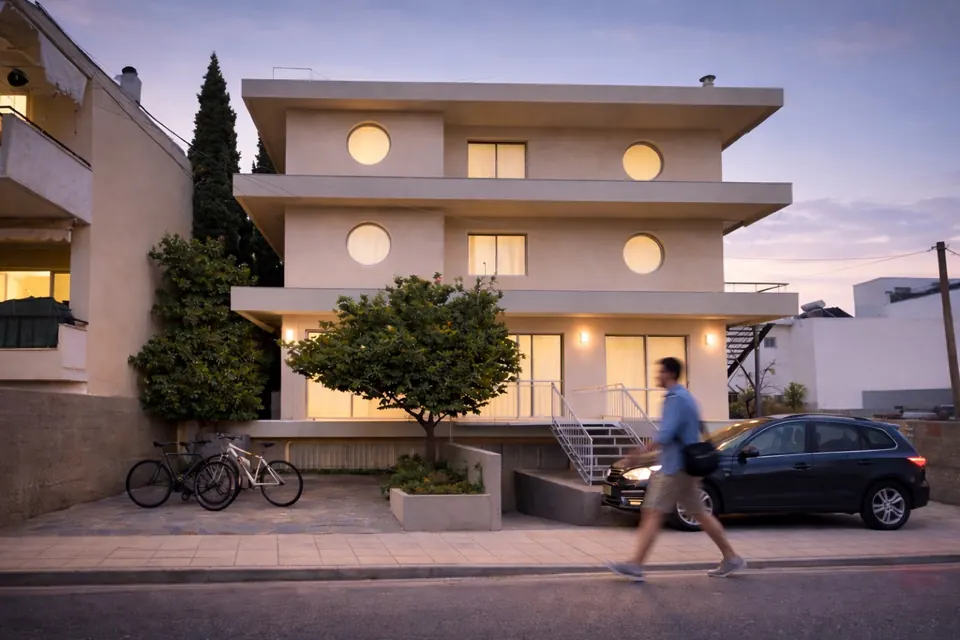
Gerakas Residences
A €250,000 Golden Visa conversion in Gerakas — an office turned into homes: compact one-bedrooms from €250,000.
- Beds
- 1 bed
- Energy Class
- —
- Delivery
- 2027