September 5, 2026 · Emre Kurt, Lawyer
What Is the Greece Golden Visa Non-Dom Regime? €100,000 Flat Tax
The Non-Dom regime (Article 5A): a flat €100,000 annual tax on all foreign income for 15 years. Golden Visa synergy, requirements and CFC risks in this 2026 guide.
The Non-Dom regime (Article 5A) is an optional tax regime Greece offers to high-net-worth investors, "capping" all foreign-source income with a flat €100,000 annual tax. Although it is a completely separate mechanism from the Golden Visa, the two create a strong synergy. In this article we explain, with current 2026 information, how the Non-Dom regime works, who it is really advantageous for, the application requirements, and the risks to watch for.
The Basic Mechanic: A Flat Amount, Not a Progressive Rate
Under the Non-Dom regime, all foreign-source income — including dividends, interest, rent, capital gains and all other income types — is capped with a flat €100,000 annual tax instead of the standard progressive rates of 9-44%. This means the tax payable stays fixed no matter how high the income. However, this umbrella covers only foreign income; Greek-source income (e.g. rental income from a property in Greece) stays outside this regime and is taxed separately at the standard progressive rate.
Who Is It Really Advantageous For? A Concrete Example
Consider an investor earning €300,000 a year abroad. In the standard progressive tax system the tax on this amount would be about €123,900, while under the Non-Dom regime the same investor pays only the flat €100,000; a saving of about €23,900 for that year. This simple maths clarifies the regime's logic: the higher your foreign income, the more advantageous Non-Dom becomes. By contrast, for an investor with lower foreign income, the standard progressive system can be cheaper; a cost-benefit calculation based on personal income level is therefore recommended before switching to the regime.
Key Requirements and Timing
| Element | Detail |
|---|---|
| Annual Tax | Flat €100,000 — for all foreign income |
| Duration | Up to 15 years |
| Family Member Surcharge | +€20,000/year per person |
| Past Residency Requirement | Not a Greek tax resident in 7 of the last 8 years |
| Investment Requirement | €500,000 (real estate/business/securities), completed within 3 years |
| Application Deadline | 31 March of the relevant tax year |
| Payment Deadline | In a single payment by 31 July |
🔑 Golden Visa Synergy: A Separate Investment May Not Be Needed
One of the most practical aspects of the Non-Dom regime is the potential convenience it offers Golden Visa investors. The €500,000 investment required to apply can be in the form of real estate, a business or securities; an exception or alternative route may be recognised for certain investment-based residence permit holders (including the Golden Visa). This means your existing Golden Visa investment may already meet this requirement and you may not need to make a separate new investment for Non-Dom. However, as this can vary by the size and type of the investment, it is important to confirm with a tax advisor whether your situation fits this exception.
⚠️ Risks to Watch For
| Risk | Description |
|---|---|
| Double Taxation | The €100,000 is not credited against tax already paid abroad |
| CFC Rules | Your foreign companies may fall under the Greek CFC regime within EU ATAD |
| Investment Continuity | An interruption longer than 6 months = immediate cancellation of status |
| Exit Tax | Your source country may continue to tax you when or for 1+ year after you leave residency |
Of these risks, the CFC (Controlled Foreign Company) rules in particular require serious planning for investors with a holding company or investment structure. Becoming a Greek resident can bring your companies abroad under the Greek CFC regime within the EU ATAD framework; in that case the company's undistributed passive profits can be attributed to you personally. A holding structure that worked during your former residence period can become a matter that needs re-examination on moving to Greece.
Competitive Comparison: One of Europe's Cheapest Flat-Fee Regimes
Greece's flat €100,000 Non-Dom fee stands out as one of the lowest-cost options among similar regimes in Western Europe. For comparison: Italy's similar regime rose to €300,000 from 2026, while Portugal's pensioner-friendly NHR regime closed and was replaced by the narrower IFICI. Greece's 7% pensioner tax rate is a candidate to fill this gap. Cyprus, meanwhile, remains an important competitor, especially for investors with heavy dividend and interest income, with its 17-year exemption period.
2026 Update: Law 5246/2025
- Greek-source income outside the Non-Dom umbrella is now taxed at the revised progressive rate.
- A 50% ENFIA (property tax) reduction was introduced for qualifying persons.
- The VAT suspension on new-build homes was extended until 31 December 2026.
- These changes have practical consequences for people in the Non-Dom regime who also earn local income in Greece (such as partial employment or rental income).
An Additional Advantage: Inheritance and Gift Tax Exemption
Non-Dom status provides full exemption from inheritance and gift tax for assets located outside Greece. This can be seen as an important additional advantage for investors with an international asset portfolio; but as the scope and application of this exemption can vary by asset type and country, consulting an expert when doing personal estate planning is recommended.
Let's take the right step toward your Greece Golden Visa together.
From choosing the right project to the application and residency, we are with you end to end.
Get a Free ConsultationFrequently Asked Questions
1. Is the Non-Dom regime part of the Golden Visa?
No, the Non-Dom regime (Article 5A) is a completely separate mechanism from the Golden Visa; one provides a residence permit while the other is a tax residency regime. However, the two can create a strong synergy: the €500,000 investment required to apply for the Non-Dom regime can be met through an exception or alternative route for certain investment-based residence permit holders (including the Golden Visa). This can mean your existing Golden Visa investment can be used for the Non-Dom application without a separate new investment; but it is important to confirm with a tax advisor whether this applies to your investment.
2. Who is the €100,000 flat tax really advantageous for?
This largely depends on your foreign income level. For example, an investor earning €300,000 a year abroad pays about €123,900 in the standard progressive system but only a flat €100,000 under the Non-Dom regime; a clear saving. But for an investor with lower foreign income, the standard progressive system can be cheaper than Non-Dom. Before switching to the regime, it is therefore recommended to do a cost-benefit calculation based on your personal foreign income level and verify it with a tax advisor.
3. What is the biggest risk of the Non-Dom regime?
One of the most critical risks is the CFC (Controlled Foreign Company) rules that arise if you have foreign companies; becoming a Greek resident can bring your companies abroad under the Greek CFC regime within the EU ATAD framework, and the company's undistributed passive profits can be attributed to you personally. Another important risk is double taxation; the flat €100,000 tax is not credited against tax already paid abroad, which can lead to some income types being taxed twice. Both of these risks require comprehensive international tax planning before switching to the regime.
4. If I dispose of my investment, do I lose my Non-Dom status?
Yes, this is a serious risk. The investment underlying the Non-Dom regime must be continuously maintained throughout the regime's duration (up to 15 years). If there is an interruption in the investment exceeding an uninterrupted 6-month period, the status is immediately cancelled and the person is removed from the regime. Investors in the Non-Dom regime must therefore closely track the continuity of their investment and consider this 6-month rule before planning any sale or restructuring.
5. How does Greece's Non-Dom regime compare with other European countries?
Greece's flat €100,000 fee stands out as one of the lowest-cost options among similar regimes in Western Europe. For comparison, Italy's similar regime rose to €300,000 from 2026, while Portugal's pensioner-friendly NHR regime closed and was replaced by the narrower IFICI. Greece's 7% pensioner tax rate is also a candidate to fill this gap. Cyprus, meanwhile, remains a strong competitor, especially for investors with heavy dividend and interest income, with its 17-year exemption period; so different countries can offer different advantages depending on the income profile.
Note: The tax information in this article is based on general regulations and can vary significantly by your personal income structure, your country of origin's tax rules and current regulations; it does not constitute tax advice. Contact us to assess together whether the Non-Dom regime suits you, its synergy with your Golden Visa investment, and the CFC/exit tax risks.
Thessaloniki Centre · ThessalonikiGA-51
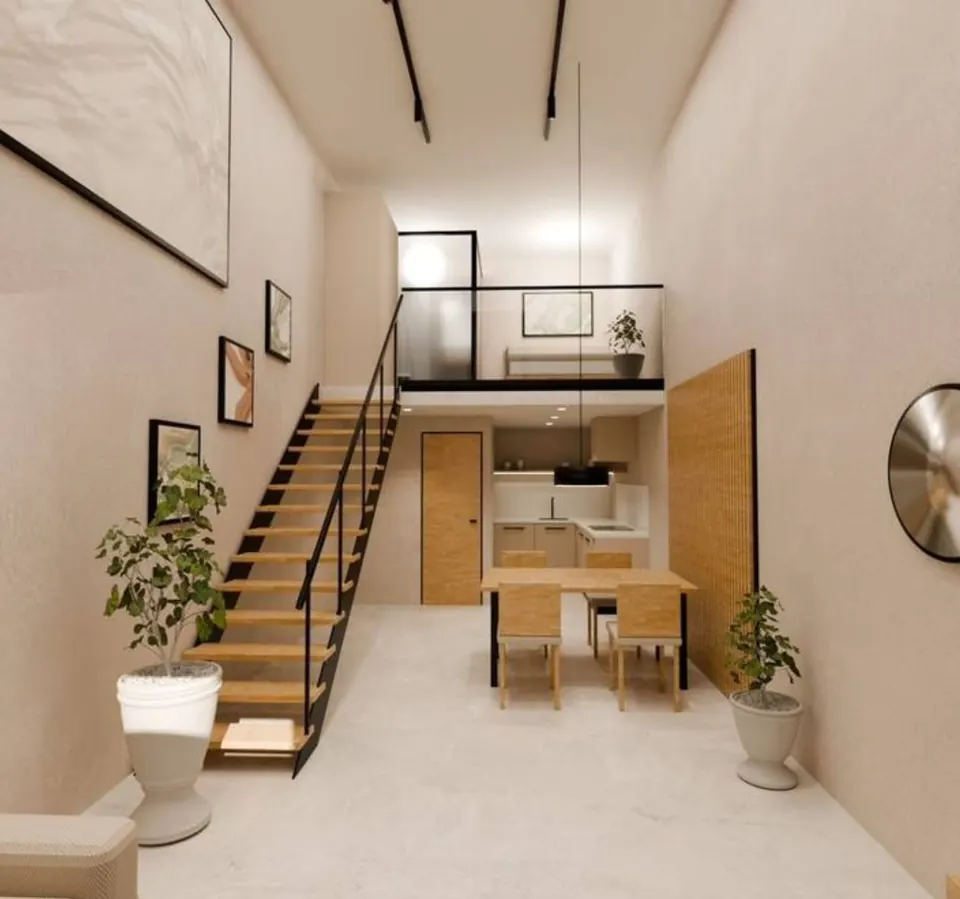
Thessaloniki City Centre Twin Lofts
Two lofts in central Thessaloniki being converted from commercial to residential use: about 70 m² each, with a double-height living space and a mezzanine bedroom. Each is Golden Visa eligible at €250,000.
- Beds
- 1 bed
- Energy Class
- A
- Delivery
- Under renovation · date on request
Peristeri · AthensGA-41
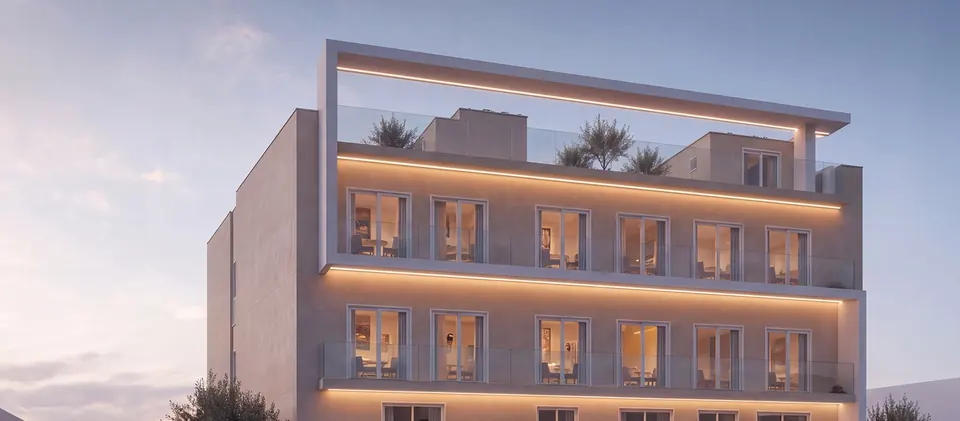
Peristeri Residences
A boutique project in Peristeri, a lively district of west Athens, where an older building is being converted into 14 apartments: 32–65 m², mostly two-bedroom, delivered furnished, with a top-floor apartment featuring a private roof terrace. Eligible for the €250,000 Golden Visa, €250,000–292,500.
- Beds
- 1–2 bed
- Energy Class
- —
- Delivery
- 2027
Gerakas · AthensGA-19
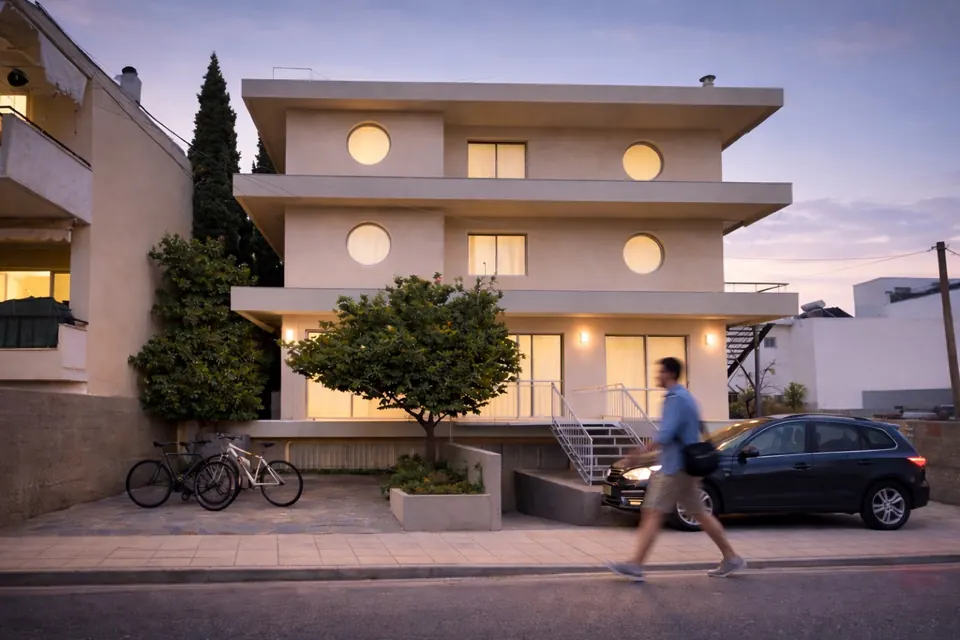
Gerakas Residences
A €250,000 Golden Visa conversion in Gerakas — an office turned into homes: compact one-bedrooms from €250,000.
- Beds
- 1 bed
- Energy Class
- —
- Delivery
- 2027