September 6, 2026 · Updated: October 7, 2026 · Emre Kurt, Lawyer
How Is Rental Income Tax Calculated in the Greece Golden Visa?
Golden Visa rental income tax 2026: 15-25-35-45% brackets, 5% automatic deduction, worked examples and the effect of residency status in this guide.
When you rent your Golden Visa property long-term in Greece, the rental income you earn is subject to a progressive tax bracket. A reform that took effect in 2026 corrected a sharp jump in the old system, reducing the tax burden for small and medium property owners. In this article we explain, with concrete examples, the current tax brackets, the step-by-step calculation method, and how residency status affects (or does not affect) rental income tax.
2026 New Rental Income Tax Brackets
The reform in force from 2026 smoothed the structure that used to jump directly from 15% to 35% by adding a new 25% intermediate bracket. This change provides up to €1,300 in annual tax reduction to about 161,587 owners:
| Bracket | Rate |
|---|---|
| First €12,000 | 15% |
| €12,001 - €24,000 | 25% (new intermediate bracket added in 2026) |
| €24,001 - €35,000 | 35% |
| Above €35,000 | 45% |
Calculation Steps
Two basic steps are followed when calculating rental income tax:
- Step 1: An automatic 5% deduction is applied to gross rental income. This is a flat rate applied without needing to document your actual expenses (like maintenance, repairs) one by one.
- Step 2: The remaining amount is taxed according to the progressive brackets above; each bracket is taxed only on the amount falling within its range, and the highest rate is not applied to all income.
Worked Examples
The table below shows the step-by-step calculation for two different gross rental income scenarios:
| Step | €30,000 Gross Rent | €50,000 Gross Rent |
|---|---|---|
| 5% Automatic Deduction | -€1,500 | -€2,500 |
| Taxable Amount | €28,500 | €47,500 |
| First €12,000 (15%) | €1,800 | €1,800 |
| €12,001-24,000 Bracket (25%) | €12,000 × 25% = €3,000 | €12,000 × 25% = €3,000 |
| €24,001-35,000 Bracket (35%) | €4,500 × 35% = €1,575 | €11,000 × 35% = €3,850 |
| Above €35,000 (45%) | — | €12,500 × 45% = €5,625 |
| TOTAL TAX | €6,375 | €14,275 |
These examples show the effective tax rate is about 21.25% for €30,000 gross rental income and rises to about 28.55% for €50,000 income; this clearly demonstrates the expected effect of the system's progressive structure.
No Resident/Non-Resident Difference
An important point for rental income tax: everyone earning rental income in Greece — whether or not a Greek tax resident — is subject to the same progressive brackets. Even a Golden Visa investor who stays under 183 days and is not considered a Greek tax resident pays tax on Greek rental income according to the same 15-25-35-45% brackets. This shows that your residency status affects only whether your worldwide income is taxed, while Greek-source rental income is taxed in Greece in all cases.
Renovation and Energy-Efficiency Incentive
There is an important tax incentive for eligible renovation and energy-efficiency spending: 40% of this spending can be deducted from income tax, spread over a 5-year period; the total deduction is capped at €16,000. This incentive offers, especially for Golden Visa investors modernising an old property or improving energy efficiency, a two-way advantage that both raises property value and reduces the tax burden.
The 2-vs-3+ Property Distinction (Short-Term Rental Only)
This distinction applies only to short-term (Airbnb-style) rental: owners letting up to 2 properties short-term without offering additional services are subject to the standard rental income brackets. However, those letting 3 or more properties short-term or offering hotel-like services (like daily cleaning, reception) are considered to be conducting a commercial activity, and this income is subject to 13% VAT. Long-term residential leases, by contrast, are not subject to VAT. As short-term rental is already banned in Golden Visa properties, this distinction does not apply to Golden Visa investors who rent their property out long-term; your long-term rental income is taxed without VAT, according to the standard brackets above.
Interaction with Special Tax Regimes: A Critical Nuance
There is an important point Golden Visa investors benefiting from special regimes like the Non-Dom regime (€100,000 flat tax) or the 7% pensioner flat tax regime should know: these special regimes apply only to foreign-source income. The rental income from your property in Greece, whatever special regime you are in, always remains subject to the standard 15-25-35-45% progressive brackets. For example, while an investor in the 7% pensioner regime has their foreign pension income taxed at 7%, their rental income in Greece is taxed separately according to the standard brackets.
The Declaration Process
- Rental income is declared with Form E1 (general income declaration) or Form E2 (the form specific to rental income).
- The declaration is made electronically through the myAADE portal.
- The annual declaration window is usually open between 16 March and 15 July.
- The declaration process requires having AFM/TaxisNet access, E9/ENFIA information, rental contract records and income/expense proof ready.
The Difference Between Rental Income Tax and ENFIA
Rental income tax is a tax applied to the income earned from your property, while ENFIA (the annual property tax) is a separate tax applied to owning the property itself, independent of income. Both taxes apply to all property owners regardless of residency status. As of 2026, a 50% ENFIA reduction was introduced for main-home owners in villages with a population under 1,500; this reduction is planned to become a full exemption in 2027, but it applies to small settlements with primary-residence status and is not directly applicable to most Golden Visa investment properties.
Let's take the right step toward your Greece Golden Visa together.
From choosing the right project to the application and residency, we are with you end to end.
Get a Free ConsultationFrequently Asked Questions
1. How is the rental income from my Golden Visa property taxed?
As of 2026, your rental income is taxed in four progressive brackets: 15% for the first €12,000, 25% for €12,001-24,000 (the new intermediate bracket added in 2026), 35% for €24,001-35,000, and 45% above €35,000. Before the calculation, an automatic 5% deduction is applied to your gross rental income; this is a flat rate applied without needing to document your actual expenses one by one. This taxation applies regardless of your residency status; whether or not you are a Greek tax resident, your rental income in Greece is subject to the same brackets.
2. What did the 2026 tax reform change?
The 2026 reform smoothed the previous structure that jumped directly from 15% to 35% by adding a new 25% intermediate bracket; this bracket applies to income between €12,001 and €24,000, while €24,001-35,000 remains at 35%. This change aims to reduce the tax burden especially for small and medium property owners; about 161,587 owners are estimated to gain up to €1,300 in annual tax reduction. This reform applies equally to both resident and non-resident property owners.
3. If I'm in the Non-Dom regime, is my rental income also within the €100,000 umbrella?
No, this is an important nuance. The Non-Dom regime (€100,000 flat tax) and similar special regimes (e.g. the 7% pensioner flat tax) apply only to foreign-source income. The rental income from your property in Greece, whatever special regime you are in, always remains subject to the standard 15-25-35-45% progressive brackets, and these two taxes are calculated and paid separately. So investors planning to switch to the Non-Dom or pensioner regime should know from the outset that their rental income in Greece will stay outside these regimes' scope.
4. What deductions can I use to lower my rental income tax?
As standard, an automatic 5% deduction is applied to gross rental income; this is a flat rate applied without documenting actual expenses. In addition, 40% of eligible renovation and energy-efficiency spending can be deducted from income tax, spread over a 5-year period; the total deduction is capped at €16,000. This incentive offers, especially for investors modernising an old property or improving energy efficiency, an opportunity that both raises property value and reduces the tax burden.
5. How does taxation change if I rent out more than one property?
For long-term rental it does not change: long-term residential leases are not subject to VAT and are taxed according to the standard rental income brackets. The 2-vs-3+ property distinction applies only to short-term rental: owners letting up to 2 properties short-term without additional services stay within the standard brackets, while those letting 3 or more properties short-term or offering hotel-like services are considered to be conducting a commercial activity, and this income is subject to 13% VAT. As short-term rental is already banned in Golden Visa properties, this rule does not apply to the long-term rental of your Golden Visa property.
Note: The tax rates and calculation examples in this article are based on general regulations and can vary by your personal situation, income level and current regulations; they do not constitute tax advice. Contact us to manage your rental income tax calculation and declaration process correctly.
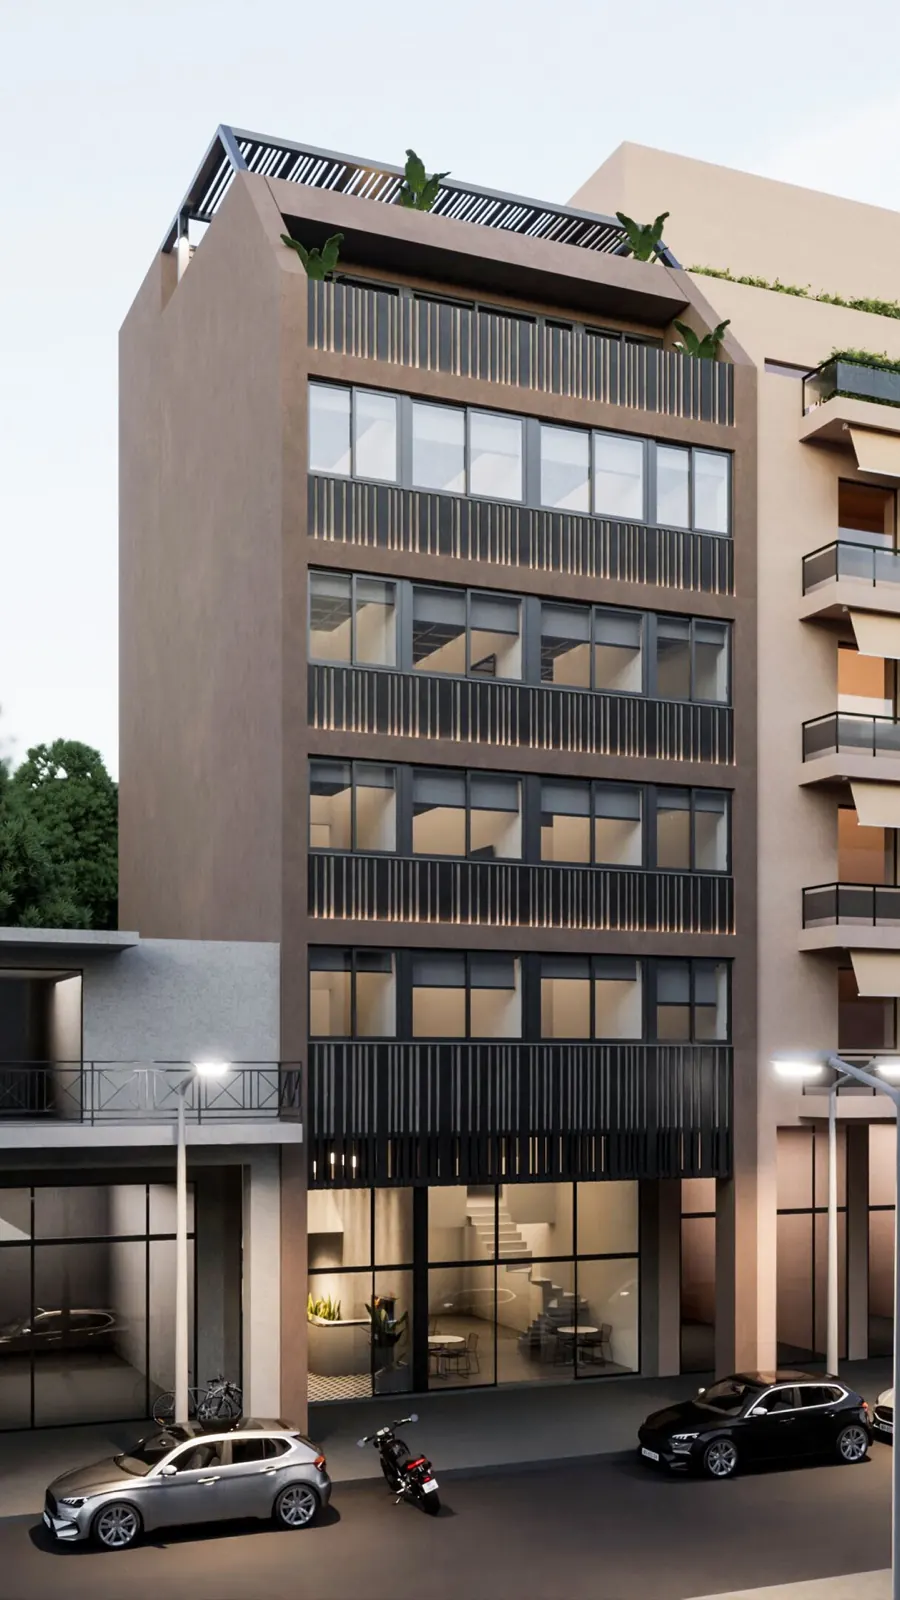 READY TO MOVE IN
Piraeus · AthensGA-04
Piraeus Furnished Apartments
A €250,000 Golden Visa conversion in the port city of Piraeus: ready, fully furnished apartments in a building with smart locks, a reception and a gym. Apartments bought for the Golden Visa can only be let long-term.
- Beds
- 1–2 bed
- Energy Class
- —
- Delivery
- Ready
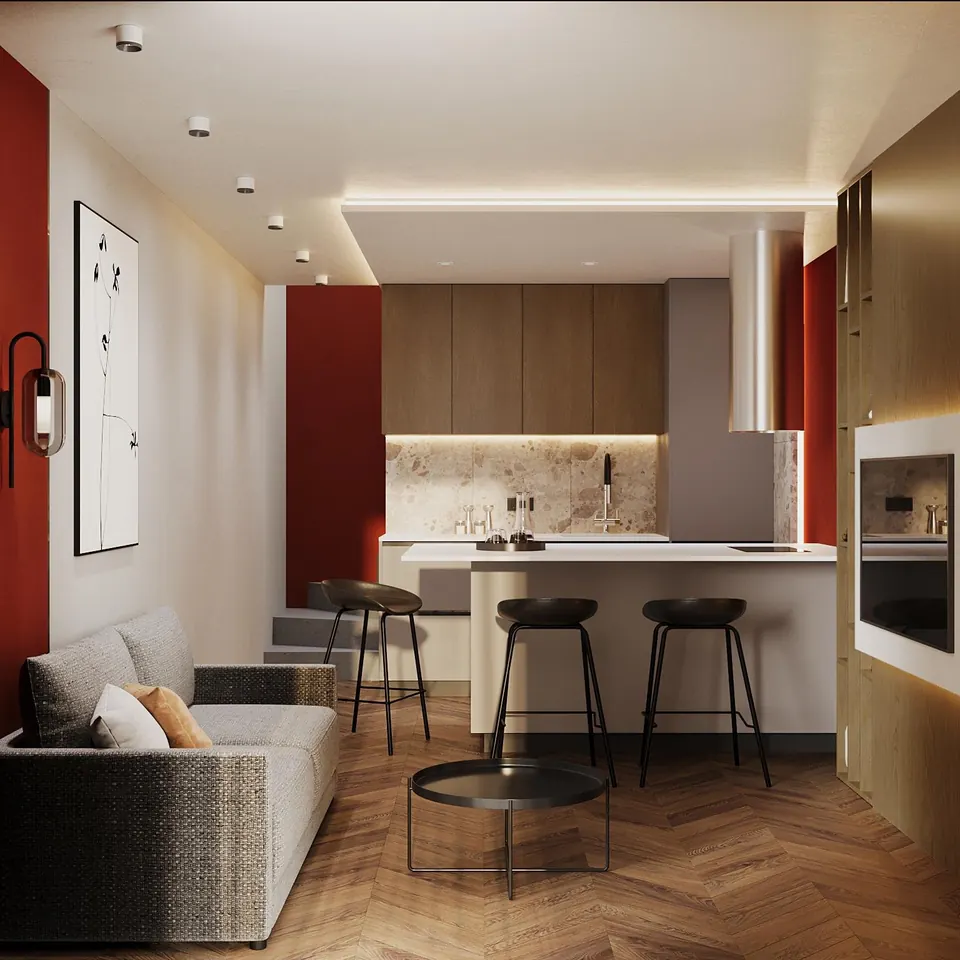 READY · TENANTED
Piraeus · AthensGA-44
Piraeus Loft Apartment
A modern, furnished two-level loft in the heart of Piraeus: 43 m², one bedroom, with a warm wood-and-red interior design. Exactly €250,000 — the minimum required for the Golden Visa.
- Beds
- 1 bed
- Energy Class
- —
- Delivery
- Tenanted
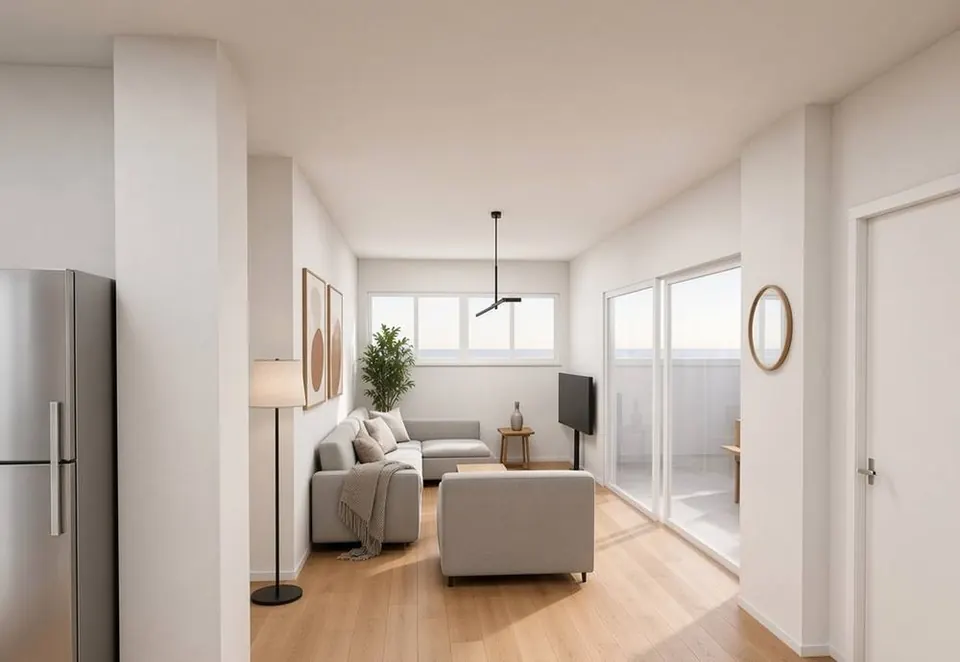 READY TO MOVE IN
Toumba · ThessalonikiGA-49
Thessaloniki Toumba Apartment
A fully renovated 74 m² two-bedroom apartment in Toumba, Thessaloniki, converted from commercial to residential use: private yard, separate storage room, energy class A. Golden Visa eligible at exactly €250,000.
- Beds
- 2 bed
- Energy Class
- A
- Delivery
- Ready